Business funding in Edinburgh
Can Edinburgh businesses get funding quickly?
Edinburgh businesses can access £5,000 to £25 million through a panel of 200+ lenders, of which 43 lend unsecured in Scotland and 32 write commercial mortgages here (checked September 2026). The second thing that shapes an Edinburgh case is the calendar. A city that earns a large slice of its year in August is read badly by any lender looking at a three-month window.

What we see from Edinburgh businesses
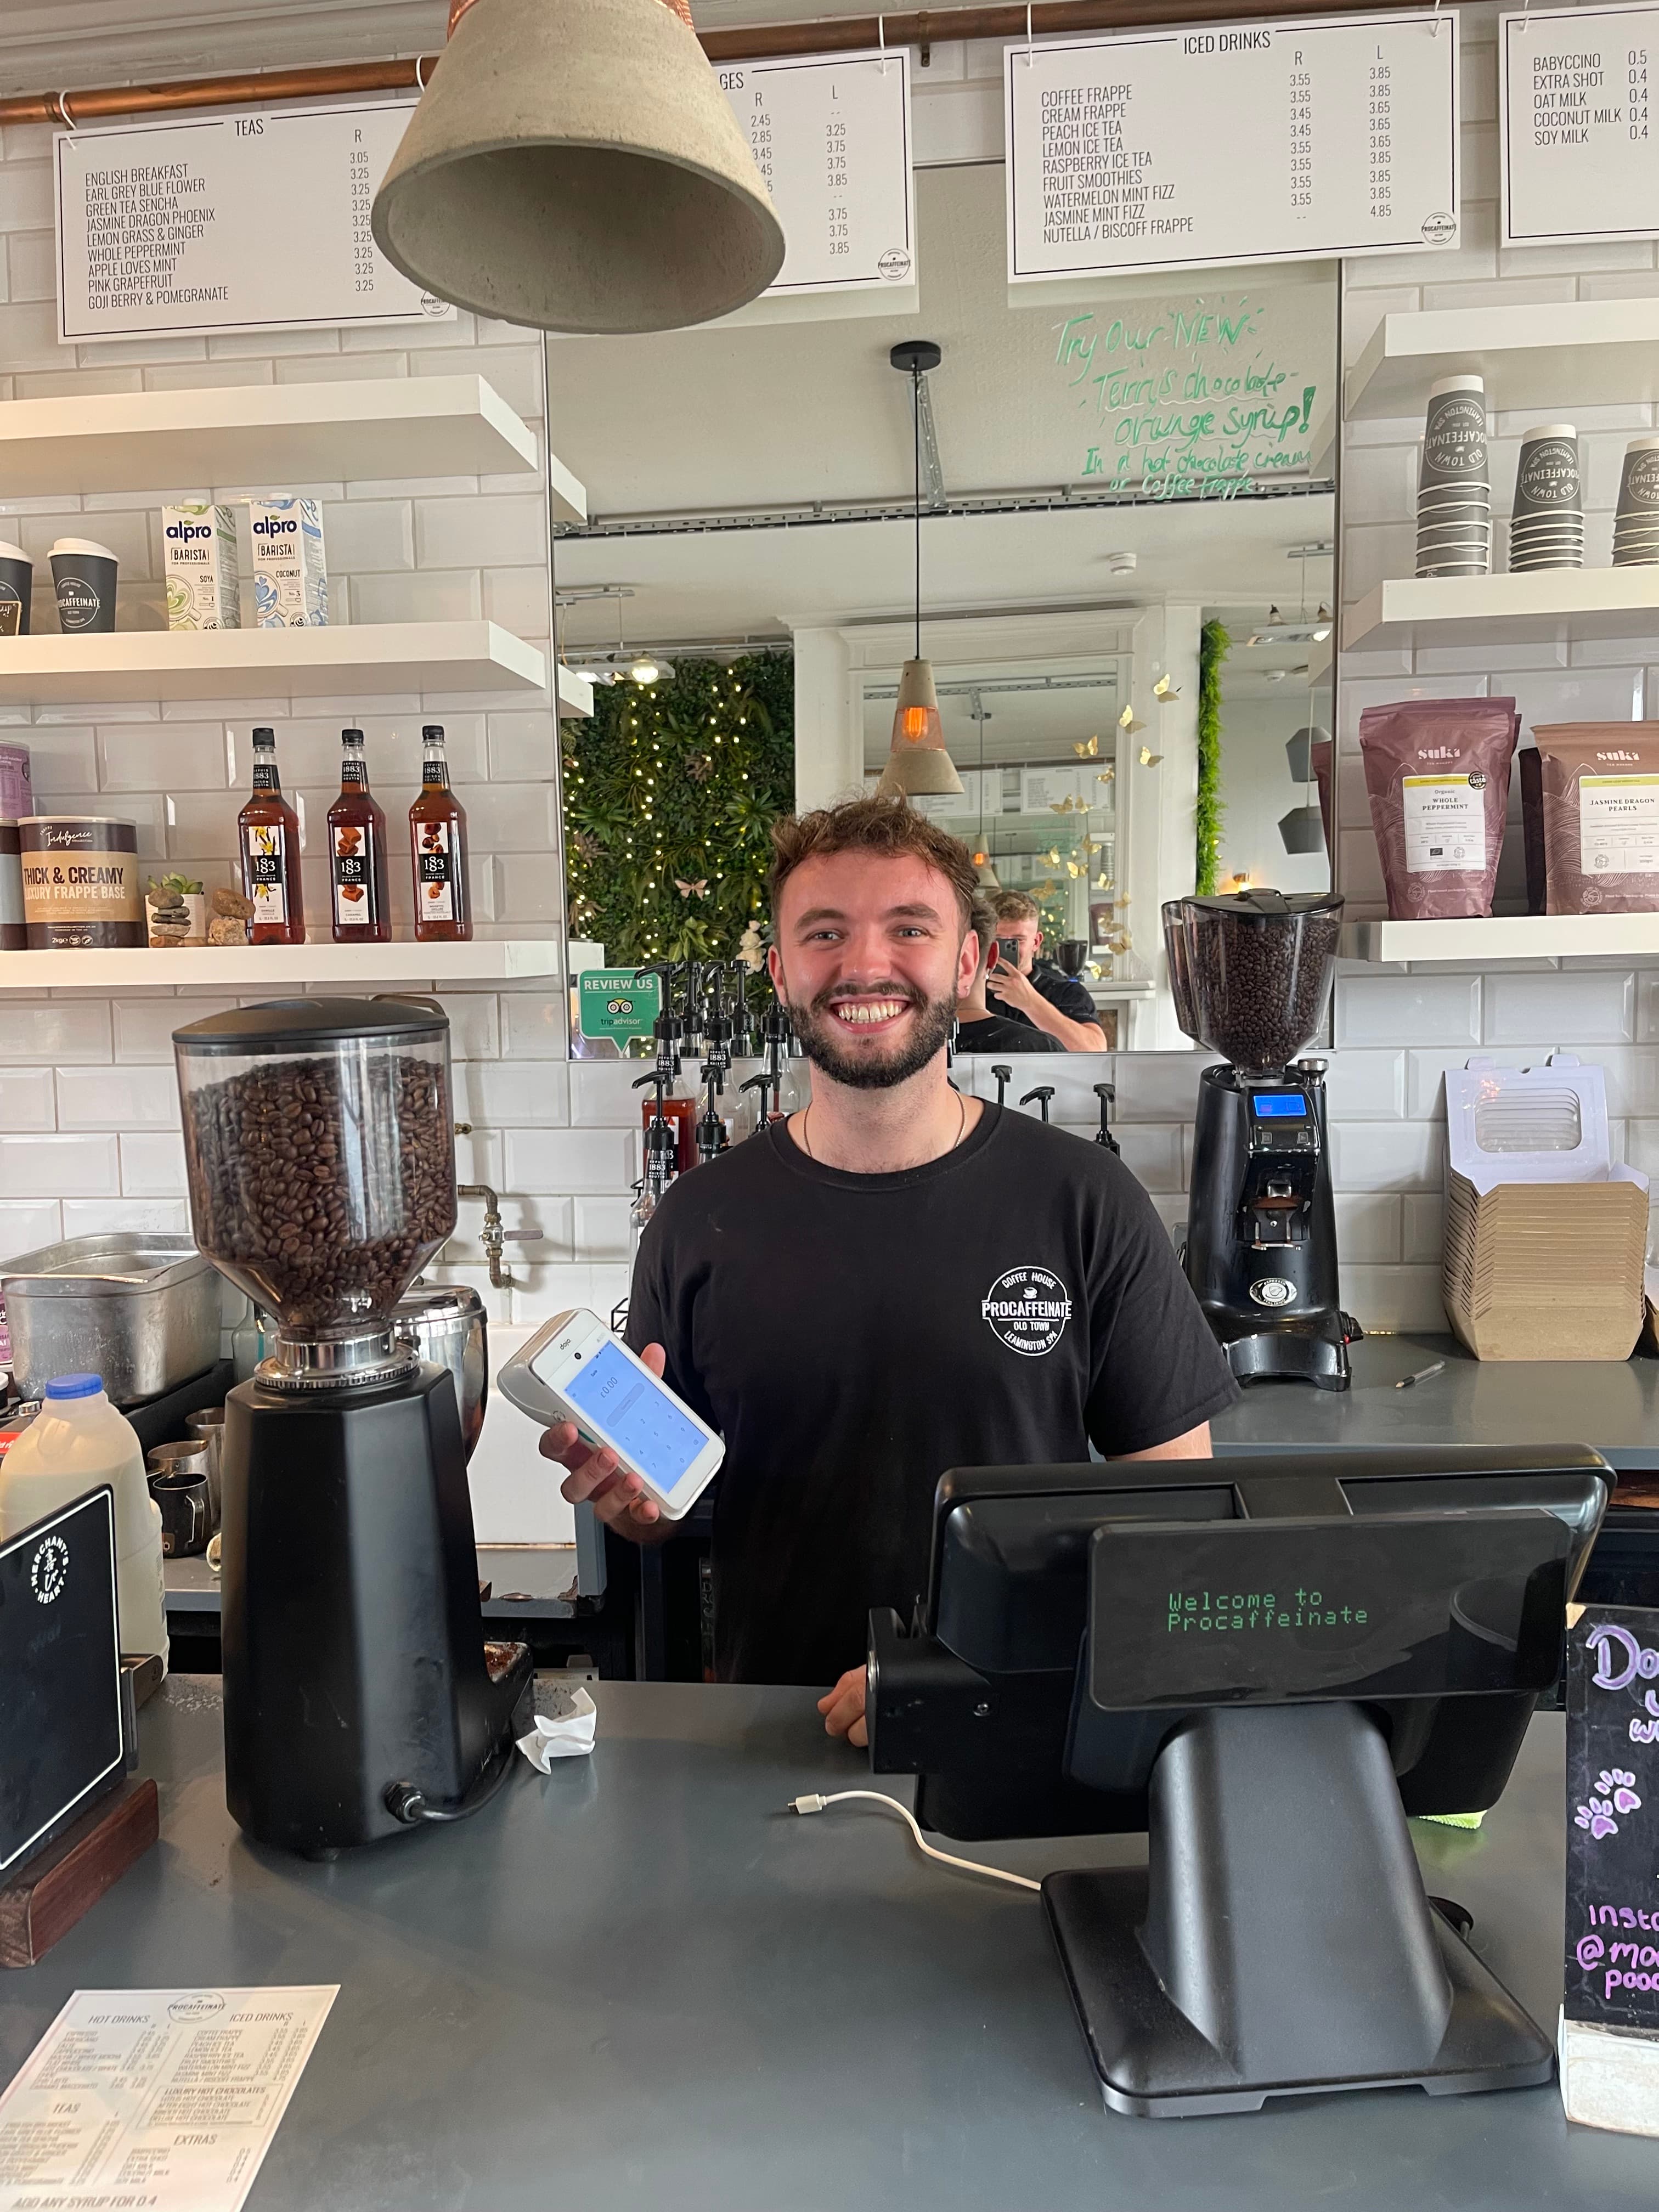
Edinburgh is the most seasonal city we work in, and that shapes everything. Cafes, bars and gift retailers in the Old Town live off tourist trade that peaks hard in August and trails off through winter. Lenders like Capify read a full year of takings rather than the last quiet month, and in our experience that is what gets seasonal Edinburgh businesses approved when their own bank says the recent numbers look thin.
The catch is timing. Businesses gearing up for festival season need stock, staff and refits paid for in June and July, before the August money arrives. That gap is exactly what a merchant cash advance covers: YouLend and 365 Finance advance against card takings and collect a percentage as sales come in, so repayments scale up in August and down in November.
Events businesses carry their own risks here. One of our Scottish clients, a florist and events firm, lost a key supplier to bankruptcy right before their busiest season and needed deposits for replacement suppliers urgently. We placed £9,500 quickly enough that they fulfilled every existing booking and kept their reputation intact. Speed was the whole deal on that one.
Away from tourism, the restaurants and bars around Leith and the offices and retailers on George Street fit the standard card-volume profile. B2B firms that invoice rather than take cards go to iwoca or Funding Circle. And Scottish limited companies qualify exactly as English ones do, same process, same timescales.
Which funding type fits which Edinburgh business?
| Funding type | Best for | Typical range | Speed (lender-advertised) |
|---|---|---|---|
| Merchant cash advance | Old Town venues and Royal Mile retail with heavy card takings | £5k to £500k | 24 to 72 hours |
| Revenue-based finance | Online sellers and subscription firms with no terminal to read | £10k to £1m | 2 to 5 days |
| Short-term business loan | Law, accountancy and fund-services firms billing on 30-day terms | £10k to £500k | 2 to 7 days |
Ranges are the span of product limits across the panel from the September 2026 extract, not what any one Edinburgh business will be offered. Speeds are what lenders advertise. The lender assesses every case on its own numbers.
Where we work around Edinburgh
Everything happens by phone and email, so there's no difference between an Old Town cafe and a workshop in West Lothian as far as the process goes. We work with businesses across Edinburgh city centre, Leith, Midlothian, West Lothian and East Lothian.
We work with UK limited companies, LLPs, sole traders and partnerships. Companies registered in Scotland are included.
Short lets, hotels and the Edinburgh property question
More Edinburgh enquiries reach us about a flat than about a business. The numbers behind that: 20 of our 28 buy-to-let lenders will lend on a holiday let, but only 11 will assess affordability on the holiday-letting income itself. The other 18 want a standard tenancy valuation instead, which on a well-run Old Town short let is a much lower figure (checked September 2026). That single criterion decides how much you can borrow more than the rate does.
Across the buy-to-let panel, published rates at 75% loan to value run 3% to 11.8% with a median of 6.1%, and at 60% the median is 6% (checked September 2026). We do not arrange lending secured on a home someone lives in, so this covers investment property held in a company or by a landlord, not your own house.
For the trading side, 31 of our lenders will lend against leisure premises and 29 against healthcare. At £50,000 unsecured across the whole panel, 47 lenders have a product covering the amount, terms run 1 to 120 months and the median published floor is 17% (checked September 2026). Apply the Scotland filter to any of those counts and it falls. Panel composition changes with every pull.
Panel counts were checked September 2026 extract, available products only. They describe the panel, not an offer.
The panel behind this page
We can place unsecured business loans cases with 55 lenders, and 200+ lenders across all products on our panel. That range matters more than any single rate: the lender that suits a five-year-old limited company with clean accounts is rarely the one that suits a seasonal business or a director with a past blip, and a broker with a shallow panel has to force your case into whichever box it holds.
Names you may recognise on the panel
Examples from our panel as at September 2026, not an endorsement of any lender and not the full list. We check criteria first and put your case only to lenders whose requirements you fit. The full panel by product is in our lender directory, and how we choose is set out on our how we work page.
Edinburgh funding questions
Can I get business funding in Edinburgh with bad credit?
Often, yes. 24 of our 55 unsecured lenders accept minor adverse older than 24 months and 8 will consider moderate adverse (checked September 2026). In Edinburgh that count is then cut again by the Scotland filter, which is why we run coverage and credit together rather than one after the other.
How fast can an Edinburgh business get funded?
A card-led advance can be decided the same day. Anything secured on a building runs on Scottish conveyancing, which is a different process with different paperwork and takes weeks rather than days. For a venue stocking and staffing up before August, start the property conversation in spring and the working capital one in June.
Does seasonal festival trade count against me?
It counts against you only if the lender reads three months instead of twelve. Edinburgh is the sharpest seasonal city we deal with: a venue can take a quarter of its year in five weeks, and a three-month statement window landing in February makes a healthy business look like a failing one. Ask for a twelve-month view and say up front which weeks are the festival. That one sentence changes offers.
Do Scottish limited companies qualify?
Yes. Scottish limited companies and Scottish LLPs go through the same process as companies registered anywhere else in the UK, and most of the panel lends north of the border: 43 of our 55 unsecured lenders, 33 of 38 asset finance lenders and 35 of 53 bridging lenders cover Scotland (checked September 2026; panel composition changes over time). We check the Scotland box before your case goes anywhere.
Is this service free?
Yes, free to you. The lender pays us when a deal completes and it does not change what you pay. You are never obliged to accept an offer, and nothing is sent anywhere without your say-so.
Do you work with sole traders in Edinburgh?
Yes. We work with sole traders and partnerships as well as limited companies and LLPs for business loans, asset finance, invoice finance and merchant cash advances. Property-secured lending (commercial mortgages, bridging, development and buy-to-let) is for limited companies and LLPs only. Lender criteria differ by structure, so tell us how you trade and we will go to the right part of the panel.
See what your business could access
Two minutes, and enquiring does not affect your credit score. We come back with the lenders that cover Scotland and match your figures, usually inside one working day.
Start the formCapExpand Ltd (FRN 1060885) is an Appointed Representative of White Rose Finance Group Limited, which is authorised and regulated by the Financial Conduct Authority (FRN 630772). We are a credit broker, not a lender. We do not provide financial advice.