Business loans and funding in Newcastle
Can Newcastle businesses get funding quickly?
Two kinds of Newcastle case reach us: weekend-heavy bars along the Quayside and through Grainger Town, and engineering and offshore supply firms across Tyneside that need a machine financed rather than an advance. Our panel of 200+ lenders covers £5,000 to £25 million and both kinds, with 20 lenders that lend against a pub and 31 that fund factory plant (checked September 2026).

Business loans in Newcastle
A business loan in Newcastle is arranged across our panel of 200+ lenders, and the products the city's searches ask for are the unsecured term loan, asset finance for Tyneside plant and a card-split advance for the Quayside: 55 lenders write unsecured loans and 38 write asset finance (checked September 2026). Each case goes only to the lenders whose published criteria it meets, and each of those makes its own decision.
Our single office is in Annesley, Nottinghamshire, a long way down the A1, and a named case handler runs every Newcastle case by phone and email. A Byker workshop and a Jesmond cafe therefore get the same turnaround, and the credit broker in the middle is paid by the lender on completion rather than by you.
What we see from Newcastle businesses
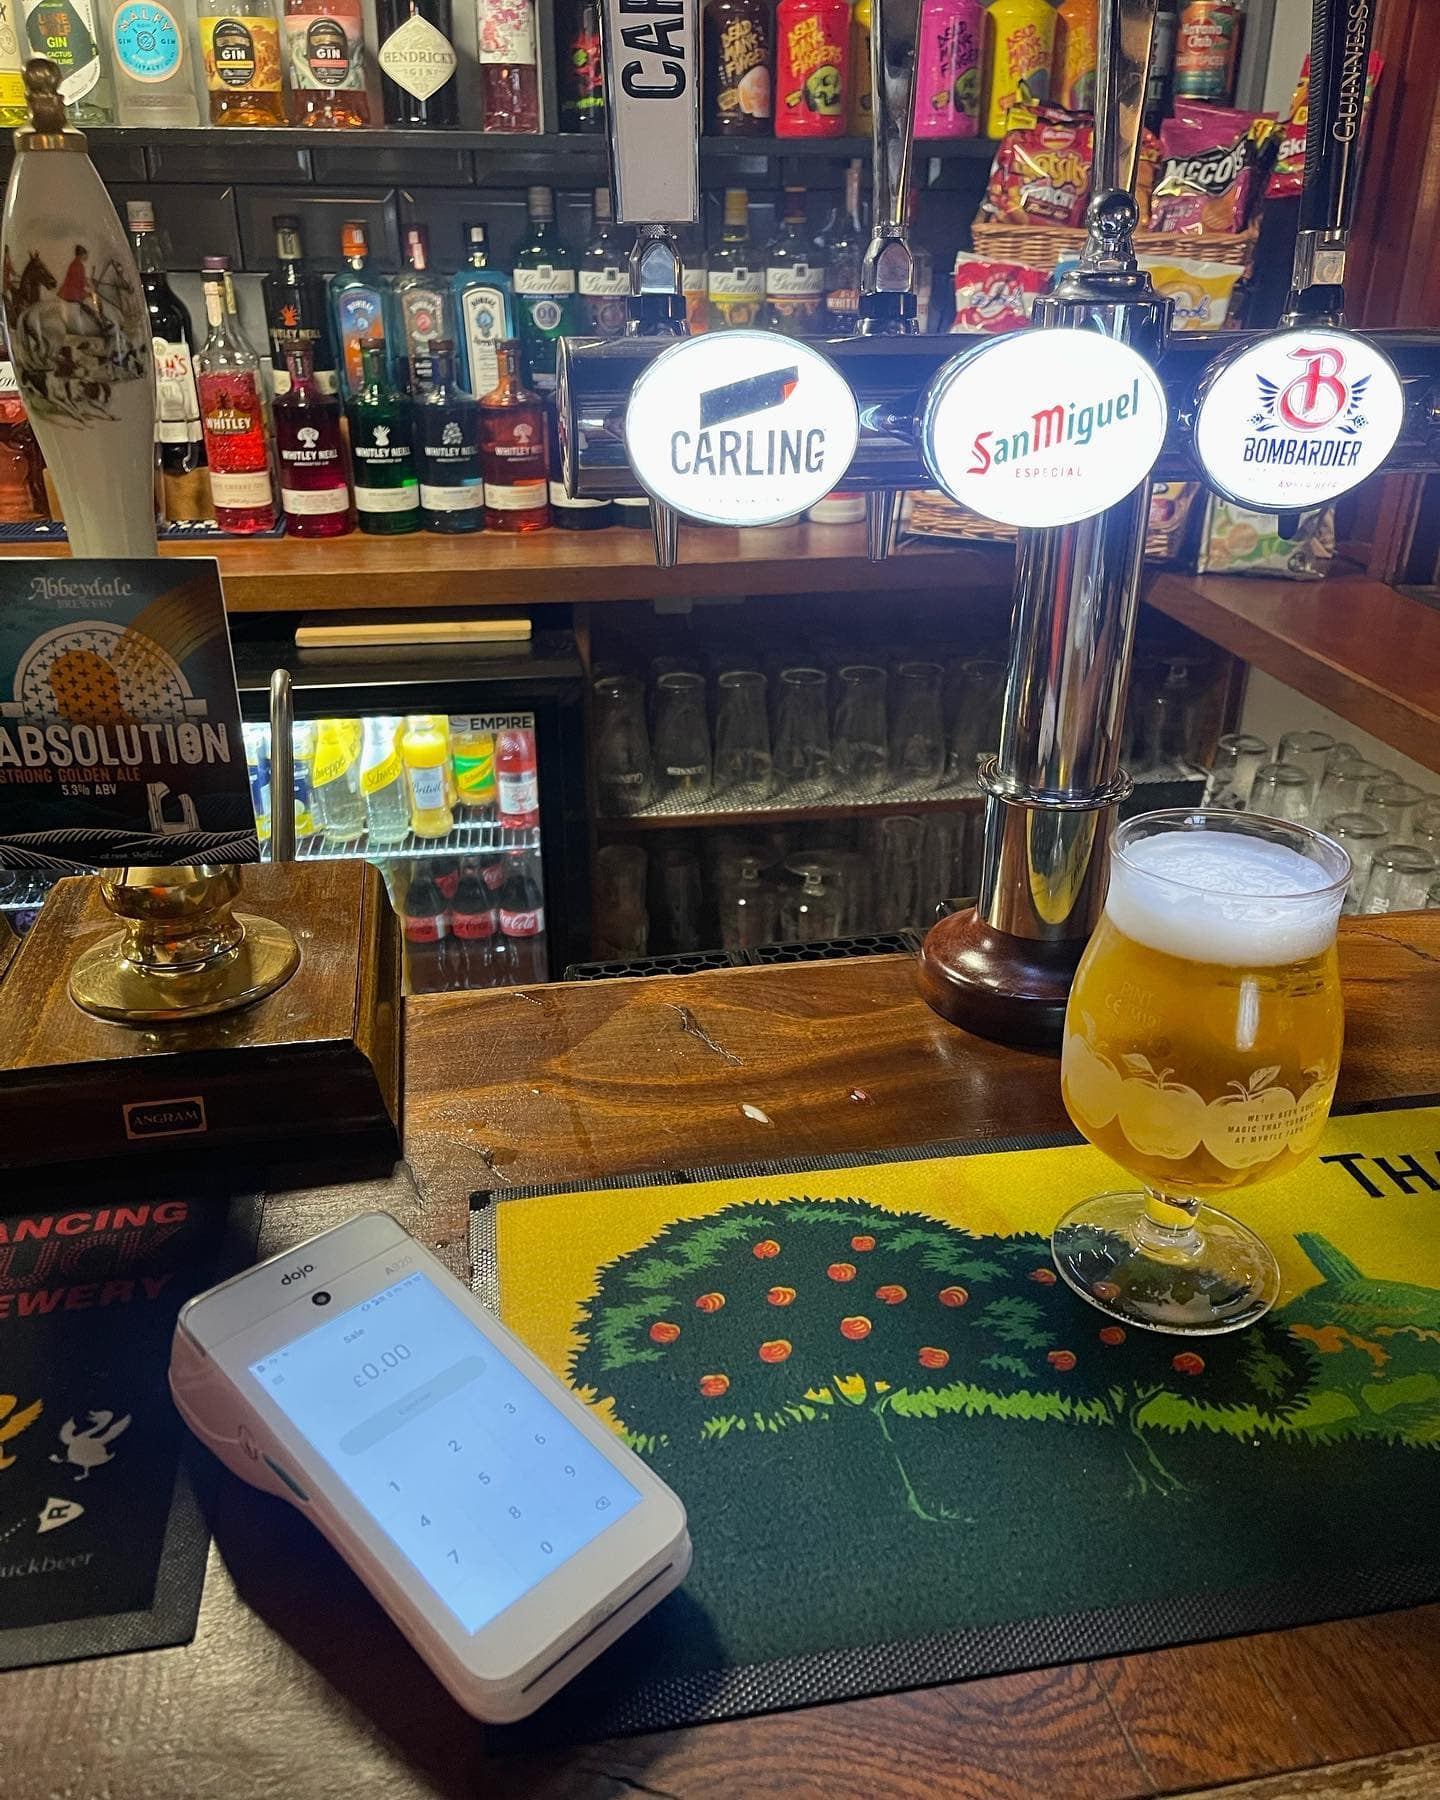
Newcastle enquiries are dominated by wet-led hospitality: bars along the Quayside and through Grainger Town where trade is heavily weighted to Friday and Saturday nights. That weekend spike puts some lenders off, but advance repayments flex with card takings, so a venue repays more on a big Saturday and less midweek. YouLend and 365 Finance both read that pattern sensibly rather than penalising it.
The most instructive North East deal we can share is a pub that decided to pivot to a food-led model. They needed £22,000 for commercial kitchen equipment, chef recruitment and an initial marketing push. The funding went through on the strength of their existing takings, the pivot worked, and the business came out with a broader customer base than the drinks-only model gave them. The catch is you need solid current trade to fund a pivot; lenders back the numbers you have, not the plan on its own.
Beyond the city centre, the cafes and independents around Jesmond fit the classic card-volume profile, and we see a steady flow of trades and B2B firms across Tyneside. Those invoice rather than take cards, so we route them to iwoca or Funding Circle from day one instead of wasting time on an advance that cannot be sized. The lenders on our panel price the takings, not the postcode.
Which funding type fits which Newcastle business?
| Funding type | Best for | Typical range | Speed (lender-advertised) |
|---|---|---|---|
| Merchant cash advance | Quayside bars and Grainger Town venues with weekend-heavy card trade | £5k to £500k | 24 to 72 hours |
| Asset finance | Machine tools, plant and workshop kit for Tyneside engineering firms | £1,000 to £50 million | 3 to 10 days |
| Commercial mortgage | Buying the pub, workshop or unit the business already trades from | £25,000 to £50 million | 4 to 12 weeks |
These ranges are panel product limits rather than typical offers, and the speeds are what lenders advertise for a clean case. Your own figures decide the rest.
What lenders see in Newcastle
Newcastle upon Tyne had 8,885 enterprises in 2025, up from 8,705 in 2024, and the size split explains a lot: 7,550 micro, 1,060 small, 190 medium and 90 large (ONS via Nomis NM_142_1, read 8 September 2026). Tyne and Wear held 29,205 and the North East Combined Authority area 55,170. The top three sectors are professional, scientific and technical at 1,475 enterprises, wholesale and retail at 1,260 and accommodation and food at 970, with construction close behind at 930. That 970 is the Quayside and Grainger Town trade, and it is a bigger share of the city than in most places we work.
The open scheme for the North East is the Northern Powerhouse Investment Fund II, a £660m British Business Bank fund whose page reads “Open for applications” on 8 September 2026. NEL Fund Managers handles both the smaller loans of £25,000 to £100,000 and debt from £100,000 to £2m here, with Maven on equity to £5m, and the launch release of 21 March 2024 named Durham, Northumberland, Tyneside and Sunderland within its reach. It is public money applied for through NEL, not a CapExpand product. The North East Growth Hub, run by the mayoral authority on 0191 561 5468, is the other public door, and the combined authority's Local Growth Plan 2025 to 2035 commits a £70m North East Investment Fund it expects to seed £390 million over 15 years across a minimum of 470 businesses.
The British Business Bank's Nations and Regions Tracker 2025 put North East external finance use at 44% in 2024, eight points lower than the year before and “the largest drop in the use of a range of traditional finance types”, even as equity deals rose 8.6% to 63. The Bank of England's Agents' summary for July 2026 reported that “Asset finance and invoice discounting facilities are growing”, which is the North East pattern in one line: fewer firms borrowing unsecured, more of them financing a machine or a ledger. Against a regional economy the growth plan sizes at £54 billion across 55,000 businesses, that shift is what a Newcastle file lands into.
Where we work in the North East
Newcastle, Gateshead, Sunderland, North Tyneside and the rest of the North East reach us by phone and email from Nottinghamshire, and a Washington haulier is handled the same way as a Quayside bar. The region's 72,875 enterprises (Nomis, 2025) are a patch we place cases across, not one we claim an office in.
We work with UK limited companies, LLPs, sole traders and partnerships.
Why engineering cases go a different route
A Tyneside fabricator buying a press brake has no reason to borrow against turnover. The machine secures the borrowing, the term matches the working life of the kit, and the cost is normally well below an unsecured facility. 33 of our asset lenders fund construction plant, 31 fund factory plant and 15 will look at older machinery, which is the one that matters for second-hand purchases (checked September 2026).
Hospitality is the mirror image. Repayment as a share of takings is what makes a thin Tuesday survivable, and it is why we still place advances for Quayside venues even though the headline cost is higher. At £25,000 unsecured, 36 panel lenders cover the amount with published rates from 4.1% to 70.8% (checked September 2026). The right answer depends on whether your income wobbles week to week.
Counts here were checked September 2026, available products only, and describe the panel on that date rather than an offer; panel composition changes over time.
The panel behind this page
We can place unsecured business loans cases with 55 lenders, and 200+ lenders across all products on our panel. That range matters more than any single rate: the lender that suits a five-year-old limited company with clean accounts is rarely the one that suits a seasonal business or a director with a past blip, and a broker with a shallow panel has to force your case into whichever box it holds.
Names you may recognise on the panel
Examples from our panel as at September 2026, not an endorsement of any lender and not the full list. We check criteria first and put your case only to lenders whose requirements you fit. The full panel by product is in our lender directory, and how we choose is set out on our how we work page.
Newcastle business loan questions
Can I get a business loan in Newcastle if the trade is weekend-heavy?
Yes. A business loan in Newcastle is placed with the lenders on our panel of 200+ whose criteria the case meets, and for a Quayside venue that is usually a card-split advance, where repayment moves with takings, rather than a fixed-instalment term loan (checked September 2026; panel composition changes over time). We arrange, the lender decides, and it pays our commission on completion.
Can I get business funding in Newcastle with bad credit?
Frequently, yes. 24 of our 55 unsecured lenders accept minor adverse older than 24 months (checked September 2026). Asset lenders go further, because the machine is the security: 19 will fund a business that filed a loss. For a weekend-led Quayside venue, the terminal record does most of the talking.
How fast can a Newcastle business get funded?
Advance decisions are advertised same-day, with funds following within days. Asset finance on a machine typically runs to a week or two once the invoice and supplier details are in. A Quayside bar and a Gateshead workshop start at the same point, but they finish on different timetables.
Which lenders fund Newcastle pubs and bars?
Weekend-weighted trade is not a problem for a card-split lender, because repayment moves with takings rather than sitting fixed on a Tuesday. What matters more is whether the terminal history is long enough, since most of the panel wants several months of it before pricing anything.
Can I use funding to change my business model rather than grow it?
Yes. A North East pub we worked with used £22,000 to pivot to a food-led model, covering kitchen equipment and chef recruitment. Lenders backed it because the existing takings were solid, and the pivot broadened the customer base.
Is this service free?
Yes, free at the point of use. The lender pays our commission when a deal completes, at no cost to you, and you are under no obligation to take an offer. Funding is subject to status and the lender's own checks.
Do you work with sole traders in Newcastle?
Yes. We work with sole traders and partnerships as well as limited companies and LLPs for business loans, asset finance, invoice finance and merchant cash advances. Property-secured lending (commercial mortgages, bridging, development and buy-to-let) is for limited companies and LLPs only. Lender criteria differ by structure, so tell us how you trade and we will go to the right part of the panel.
See what your business could access
Two minutes on the form and enquiring does not affect your credit score. You get a straight read on which lenders fit, which do not, and what each one will want to see before it decides.
Start the formSources and references
North East figures were read on 8 September 2026 on the 2023 local authority boundary; the combined authority's evidence hub uses a private-sector basis and shows 8,855, so the two series are not mixed here.
- ONS, UK business: activity, size and location 2025 (24 September 2025)
- ONS UK business workbook 2025 (Nomis dataset NM_142_1), Newcastle upon Tyne, Tyne and Wear and North East counts
- British Business Bank, launch of Northern Powerhouse Investment Fund II, 21 March 2024
- British Business Bank, Northern Powerhouse Investment Fund II
- British Business Bank, Nations and Regions Tracker 2025 (7 October 2025)
- North East Combined Authority, Local Growth Plan 2025 to 2035 (plain text PDF)
- North East Growth Hub
- Bank of England, Agents’ summary of business conditions, July 2026
- YouLend
- 365 Finance
- iwoca
- Funding Circle
- Companies House: CapExpand Ltd 14433858
CapExpand Ltd (FRN 1060885) is an Appointed Representative of White Rose Finance Group Limited, which is authorised and regulated by the Financial Conduct Authority (FRN 630772). We are a credit broker, not a lender. We do not provide financial advice.