A merchant cash advance, without the small print problem

A lump sum upfront, repaid as a share of your daily card sales. One fixed fee agreed before you sign. We arrange finance for UK limited companies, LLPs, sole traders and partnerships through the MCA lenders on our panel for £5,000 to £500,000.
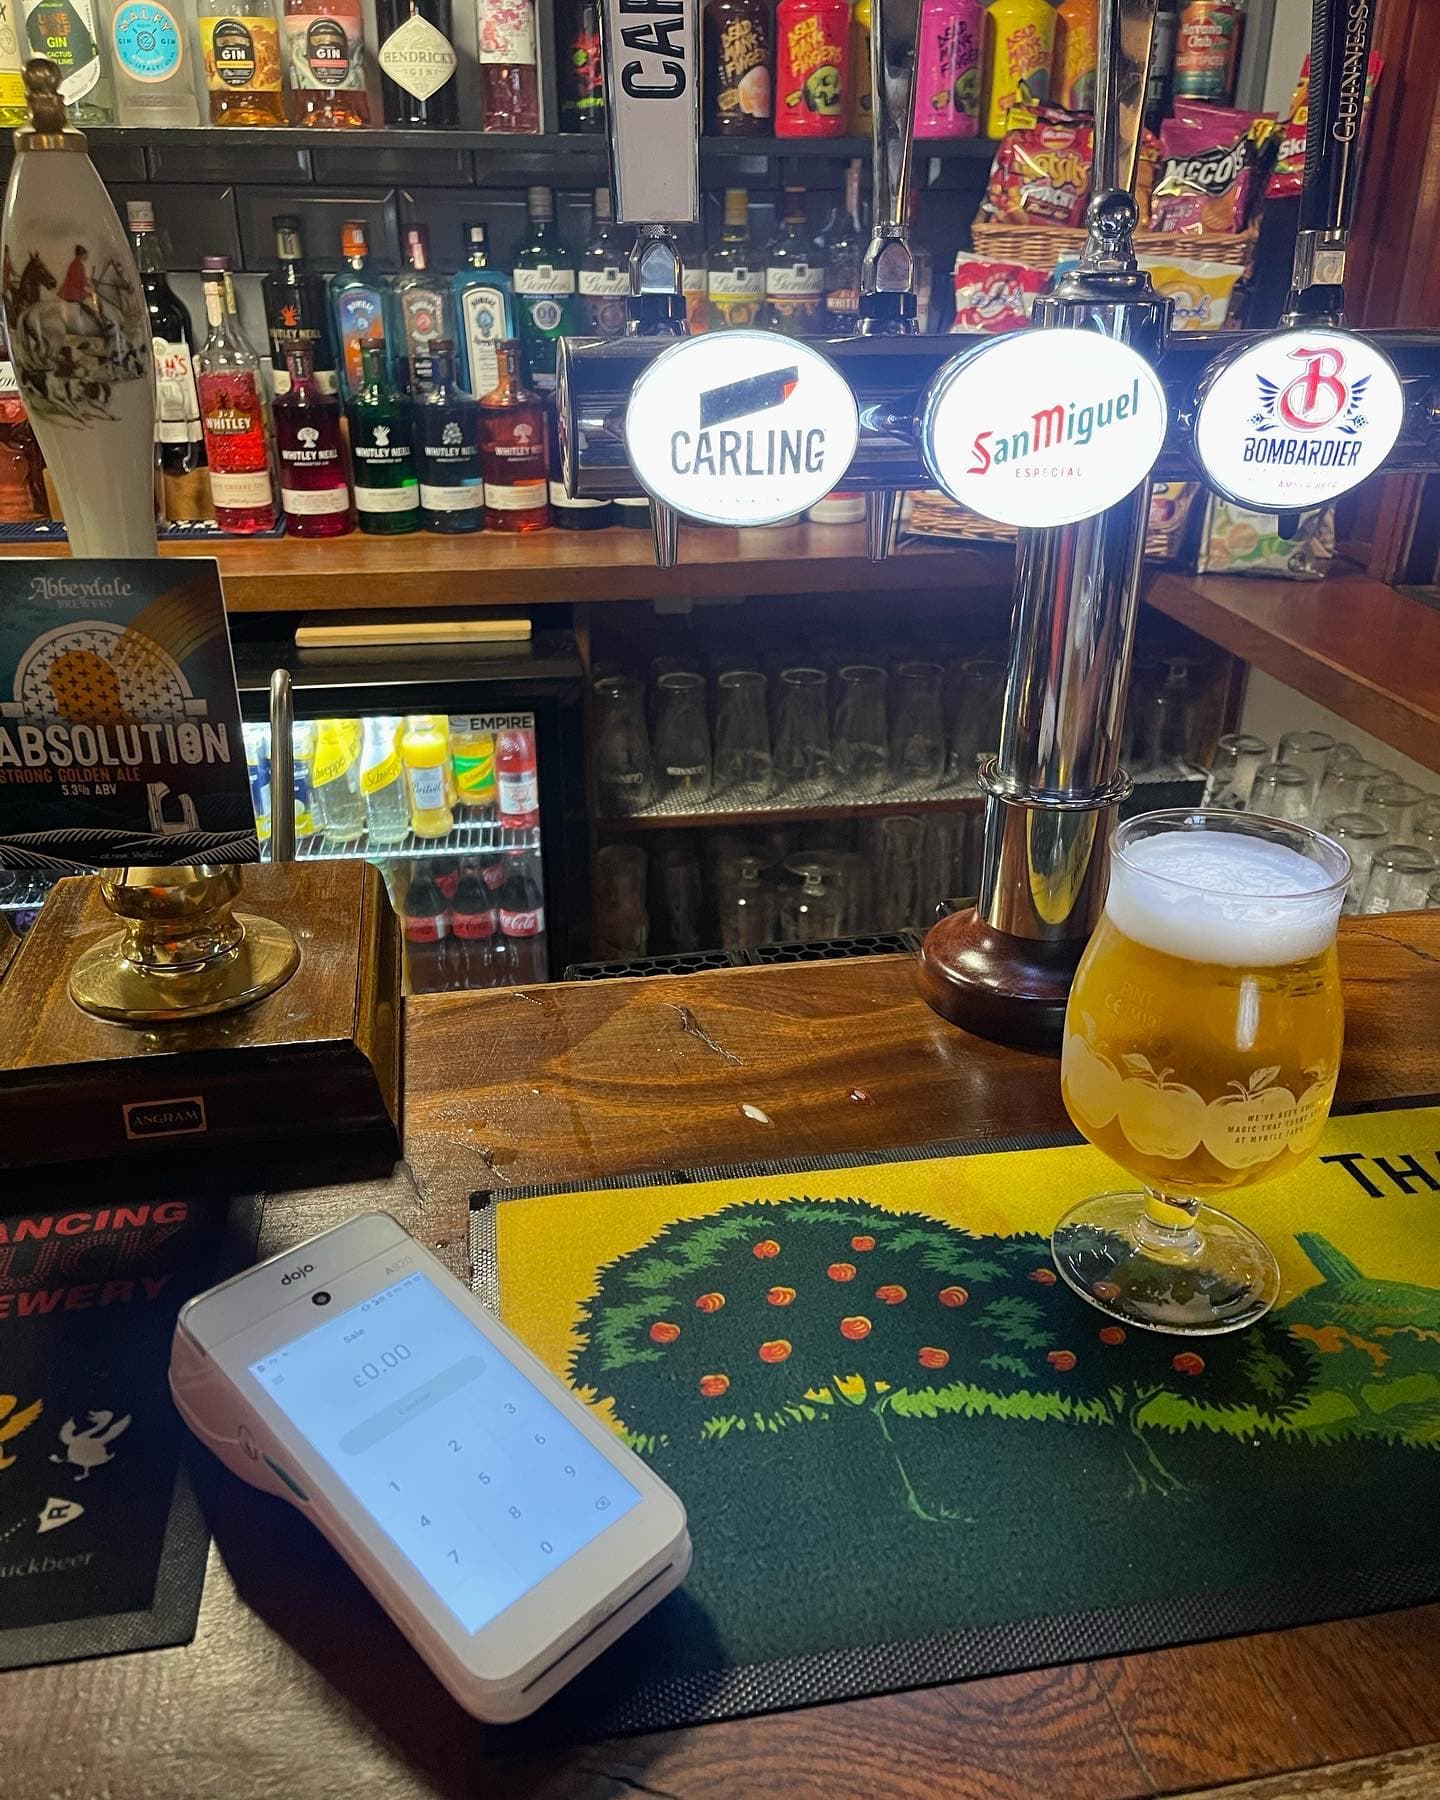
You get a lump sum upfront and repay it as a percentage of your daily card sales. Busy day, you pay a bit more. Quiet day, you pay less. One fixed fee agreed before you sign, no compounding interest, no monthly invoices that ignore your cash flow.
We introduce businesses to the MCA lenders on our panel for advances from £5,000 to £500,000. Many of them advertise 24-hour decisions; the lender makes the decision, not us.
What it is
A merchant cash advance is a lump sum of cash against your future card sales. You agree the total amount you'll repay upfront. Then a fixed percentage of every card transaction comes off the balance until it's clear.
It isn't technically a loan. You're selling a portion of future card receivables. That changes a few things. Approval is faster (often 24 hours). Credit requirements are lighter. Repayments flex with your takings, which matters more than most owners realise until they hit a quiet month with a fixed-payment loan.
Want the full breakdown including factor rates vs APR? Read our merchant cash advance guide. Or go straight to the numbers: what an MCA actually costs.
How it works
- 1
Agree the terms
You agree the advance amount, the total you'll repay (the factor rate, typically about 1.1 to 1.5), and what percentage of card sales goes to repayment. For example: £10,000 advance at 1.2 factor rate means £12,000 total repayment, with 10% of each card transaction coming off the balance.
- 2
Take payments as normal
Nothing changes for your customers or your staff. The same terminal, the same checkout. You keep taking cards exactly as you do now.
- 3
Repayments come off automatically
The agreed percentage of each card sale routes to the lender. On a £1,000 day with 10% repayment, £100 comes off your balance and £900 lands in your account.
- 4
Done when it's done
When the balance hits zero, deductions stop. Most businesses repay within 6 to 12 months. You can apply for a top-up once you've cleared 50 to 70%.
What this looks like in practice
A pub doing £40,000 in monthly card sales wants £20,000 for a kitchen refurb.
- The advance
- £20,000
- The factor rate
- 1.25
- The total to repay
- £25,000
- The repayment rate
- 12% of daily card sales
At their current turnover, they'd clear the balance in about five months. If trade dips in January, they'd repay less that month and finish a few weeks later. If summer is busier than expected, they'd finish a few weeks earlier. The total stays £25,000 either way.
How much could you borrow?
A quick estimate based on your monthly card sales. Soft check only, no obligation.
Monthly Card Sales
Your funding range
* Estimate only. Actual amount depends on your business profile and lender approval.
Could you qualify?
Two questions. Thirty seconds. No credit check at this stage.
The lenders we introduce to
We introduce merchant cash advance business to the card-split lenders on our panel, led by YouLend and 365 Finance, each with a different sweet spot. Where the MCA shape is wrong for a business, Capify’s fixed-repayment loans are the usual next step on the panel.
Merchant cash advances sit inside our unsecured panel of 55 lenders, which includes dedicated MCA providers alongside term-loan and credit-line lenders. If an advance turns out to be the wrong fit, the alternative is on the same panel and the same enquiry.
Compare every UK MCA lender side by sideCommon questions
How quickly can I receive the funds?
Most decisions come back within 24 hours. Once approved, funds typically land in your account within 24 to 48 hours. The whole process from application to money in the bank usually takes 1 to 3 working days.
Can I get an MCA with bad credit?
Often, yes. MCA lenders weight recent card sales performance heavily and credit history lightly. Businesses declined by a bank for credit reasons frequently get approved for an MCA. We'll tell you straight if your profile won't fit.
Are personal guarantees required?
Yes. Every merchant cash advance lender we introduce to asks for a personal guarantee. That makes you personally liable for the outstanding amount if the business cannot repay. No property is taken as security. Your account manager explains the terms in plain English before you sign anything.
Can I keep my existing card machine provider?
In most cases, yes. The lenders we introduce to work with your existing payment processor. A handful prefer their own integrations, and we'll tell you upfront if that applies to your offer.
More questions covered in our merchant cash advance guide.
Ready to see what's available?
Two minutes, no hard credit check, and we come back with numbers rather than a sales pitch.
Important information
CapExpand Ltd (FRN 1060885) is an Appointed Representative of White Rose Finance Group Limited, which is authorised and regulated by the Financial Conduct Authority (FRN 630772). We are a credit broker, not a lender, and we do not provide financial, tax or legal advice. We work with a panel of lenders whose particulars are available on request. If a deal completes the lender pays us a commission, at no cost to you; different lenders pay different amounts under different models, and we will tell you the amount for your deal on request. All lending is subject to status, valuation where applicable and the lender's own checks.
Registered office: Pure Offices, Lake View Drive, Annesley, Nottingham, NG15 0DT. Company No. 14433858.